
For Buyers
5 Steps to Getting Pre-Approved
Understand exactly what lenders look for and how to strengthen your offer before you start touring homes.
Read Guide
Whether you're preparing to buy your first home or getting ready to sell, our guides break down exactly what to expect.
Read Next
Understand exactly what lenders look for and how to strengthen your offer before you start touring homes.
Read Guide
Pricing strategy can make or break your timeline. Here's how we analyze comps to land on the right number.
Read Guide
What's happening with inventory and pricing across Cleveland, Dayton, and Benton this year.
Read Guide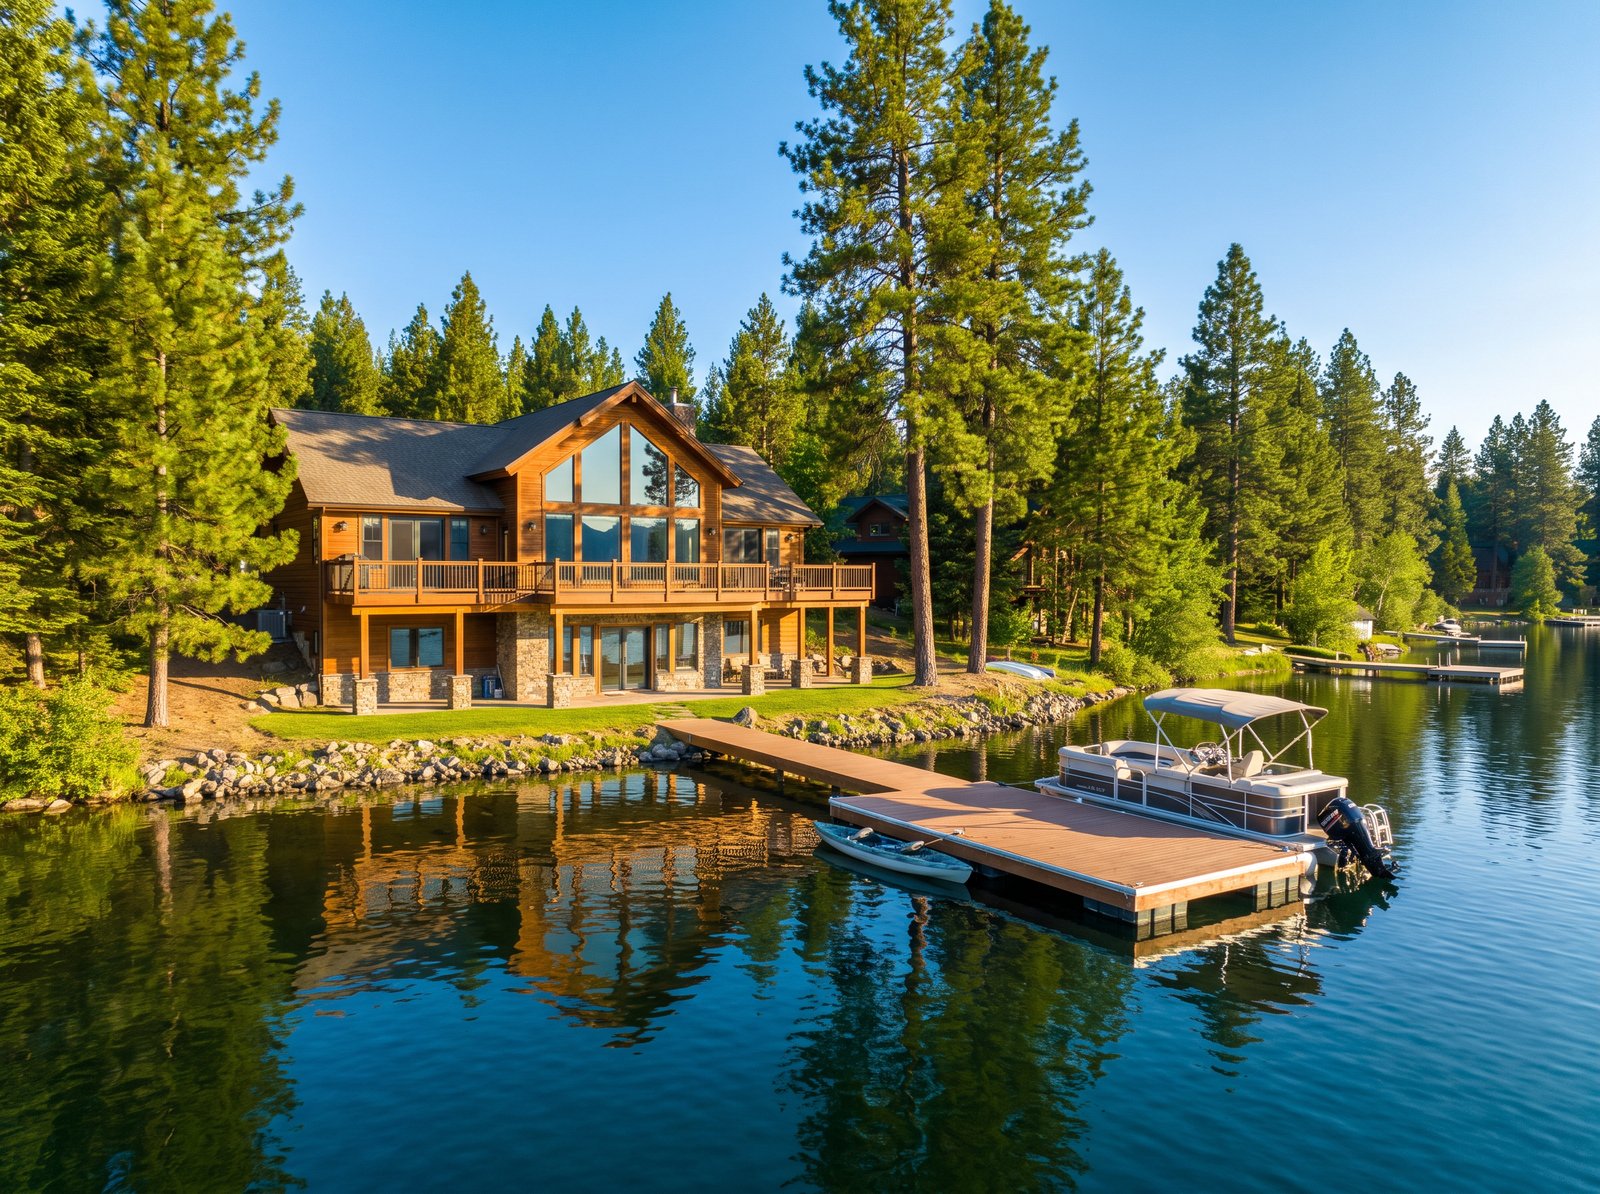
Insurance, dock permits, and flood zones — the extra checklist items for lakefront homes.
Read Guide
The key numbers to run before buying an investment property, explained simply.
Read Guide
Small, high-ROI projects to tackle before your home hits the market.
Read GuideCommon Questions
It depends on your loan type. Conventional loans typically require 5–20% down, while FHA loans can go as low as 3.5%. Our mortgage calculator on the homepage is a great starting point for estimating your monthly payment at different down payment levels.
Most closings take 30–45 days from an accepted offer, depending on financing, inspections, and appraisal timelines. Cash transactions can close in as little as two weeks.
We strongly recommend it. A licensed inspector can flag issues with the roof, foundation, HVAC, and more — giving you leverage to negotiate repairs or price before closing.
Pre-qualification is a quick, informal estimate based on self-reported financials. Pre-approval involves a lender verifying your income, assets, and credit — making your offer far more competitive with sellers.
We run a comparative market analysis (CMA) using recently sold, active, and pending listings in your immediate area, adjusted for your home's condition, upgrades, and lot size.